Form E Example: Completed Sample Answers, Section by Section
See a realistic fictional Form E example with completed sample answers for property, accounts, pensions, income, needs, supporting documents and the final consistency checks.
Fill in your Form E online, with guidance at every step
Divvio turns your answers into a completed Form E PDF. Answer straightforward questions about your finances, save your progress, and return whenever you’re ready. Divvio puts your answers into the official court form.
Start free
Create an account and work through your answers at your own pace.
Autumn offer: £79 until 30 November, normally £149.
Written by
Ben Ayade
Founder of Divvio · Called to the Bar of England & Wales
Last updated
Updated 2 November 2026
Reviewed and refreshed when the article or guide is materially updated.
Why Divvio is qualified to help
Divvio is built specifically for Form E and financial remedy workflows in England & Wales.
The product includes guided Form E steps, settlement and budget calculators, document checklists, and official Form E PDF generation.
This Form E example shows what a completed financial statement can look like. It follows one entirely fictional person through the current 30-page Form E (01.23), including property equity, bank accounts, debts, pensions, annual income, monthly needs and the documents that support each answer.
Use it to understand the level of detail, calculation and cross-checking expected. Do not copy the names, figures or wording into your own form. Your Form E must disclose your own circumstances fully, frankly and clearly. This guide covers England and Wales and was checked against the official form on 11 June 2026. It is general information, not legal advice.
Important before using this example
A sample answer is a pattern, not evidence
A strong Form E answer identifies the asset or income, gives the value at the relevant date, explains any estimate, matches the supporting document and remains consistent with the totals elsewhere in the form. A polished sentence with no evidence is not a substitute for disclosure.
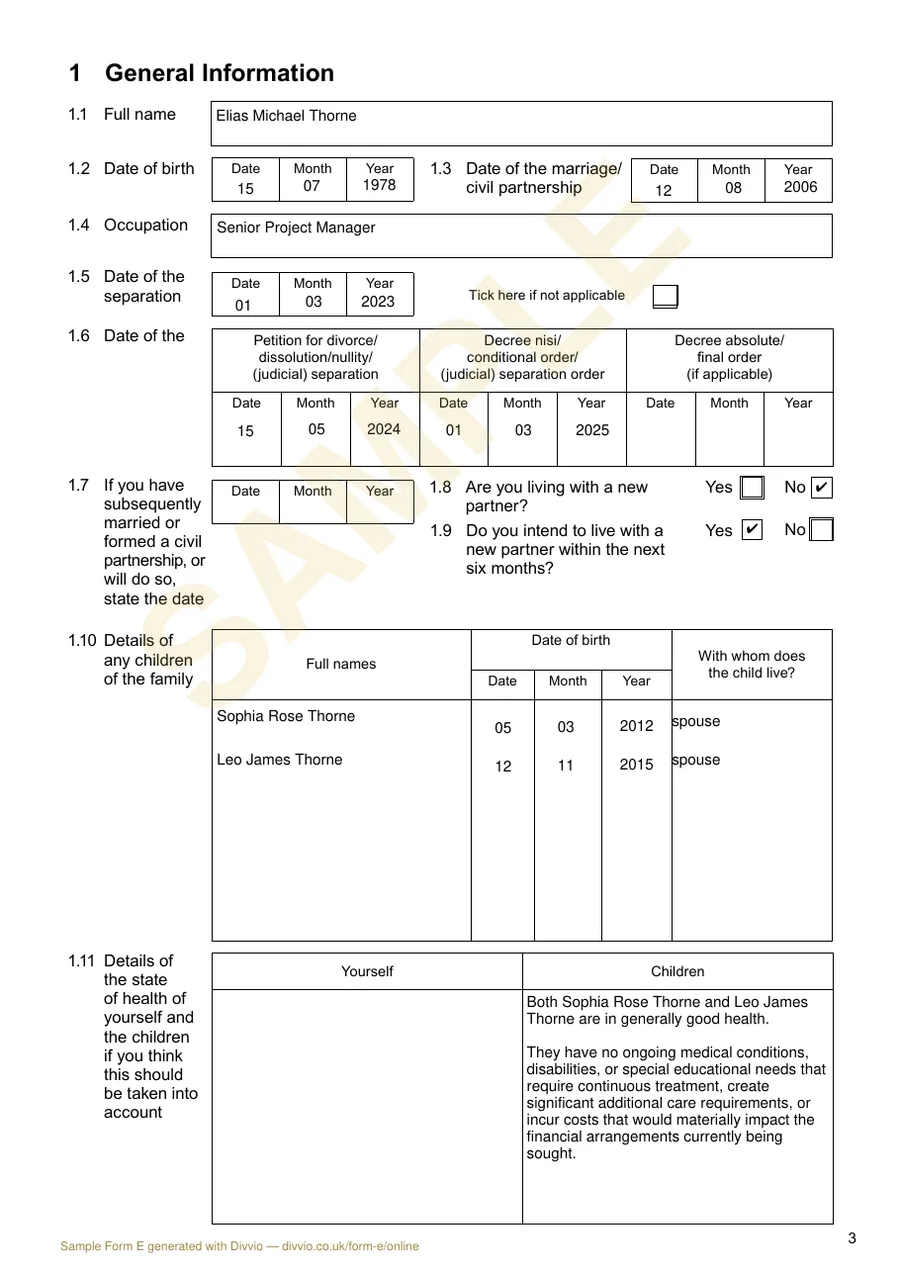
To see the finished layout first, email yourself the completed sample Form E PDF. It is a watermarked example with fictional details, not a blank form for your own answers. You can then follow the section-by-section reasoning below.
People searching for a completed Form E often want to know how much detail belongs in each box. The useful lesson is not the fictional number itself, but the method behind it:
Answer the exact question. Do not use a nearby box to avoid a difficult disclosure.
Identify the source and date. For example, say whether a property figure comes from a valuation or your own realistic estimate.
Show the calculation. Equity, joint interests and annual totals should be traceable.
Attach the required evidence. The form specifies documents for property, accounts, investments, businesses, pensions and income.
Keep every section consistent. Child maintenance mentioned in Part 1 should also appear in income. A pension in the capital summary must have a pension entry behind it.
Where a question genuinely does not apply, the first page of Form E says to write “N/A”. Leaving a box blank creates uncertainty about whether it was missed.
Is there an editable version of this Form E example?
The completed sample is a reference example; use a blank Form E or an online questionnaire for your own answers. Its fictional names and figures should not become the starting point for your disclosure.
Blank official PDF.Download Form E free from GOV.UK. HMCTS recommends downloading and saving the form, then opening it in Adobe Reader to fill it in. The publication page lists PDF downloads, not a Word version. Save your own copy and check that your answers are retained before completing the whole form.
Editable online answers.Divvio's online Form E lets you complete and edit your own answers in a guided questionnaire, then export them to the official PDF. It does not provide an editable Word export. You can start free and pay when you download your completed form.
For the official file, PDF-reader tips and continuation sheets, see the Form E template download guide. If you want to see the finished layout before starting, use the free fictional sample below.
Official download options checked on 2 November 2026. Check the GOV.UK page before starting in case HMCTS updates the form.
Free completed sample
Email me the completed sample Form E PDF
See the finished form before you start yours. Get a watermarked example with fictional details, ready to save or print. No account needed.
One email with the sample. This does not subscribe you to marketing emails.
The fictional case used in this Form E example
Alex Morgan is a fictional 42-year-old operations manager. Alex and their spouse married in August 2012 and separated in September 2025. Their two children, aged 12 and 9, live mainly with Alex. Alex remains in the jointly owned family home and receives voluntary child maintenance.
Accounts, ISA, shares and cash disclosed separately
12 months of account statements and latest investment statements
Debts
£8,880 excluding the mortgage
Latest credit card and loan statements
Pensions
Two defined-contribution arrangements totalling £105,900
Recent cash equivalent statements
Income
Employment, savings interest and child maintenance
P60, three payslips, bank records and maintenance agreement
All names, dates, addresses, account details and values below are invented. The example deliberately uses a relatively straightforward employed case. Self-employment, trusts, companies, overseas assets, disputed ownership, unusual pensions or complex tax issues require more tailored work.
Part 1 example: general information
Part 1 is factual, but it should still connect with the rest of the form. Alex would enter the actual court details and then answer the personal questions along these lines:
Form E box
Sample completed answer
Why it works
1.1 to 1.6
Alex Morgan; date of birth 14 February 1984; married 17 August 2012; operations manager; separated 1 September 2025; conditional order 12 March 2026.
Uses exact dates rather than “about” or “last year”.
1.8 and 1.9
No new partner and no intention to live with one in the next six months.
Both questions are answered rather than assumed from a blank box.
1.10
Jamie Morgan, born 18 November 2013, and Taylor Morgan, born 7 May 2017; both live mainly with Alex.
Identifies each child and the living arrangement.
1.11
“No health condition is relied upon for Alex or either child.”
Makes the position explicit instead of leaving the health box empty.
1.12
Both children attend local state schools. Jamie is expected to move to secondary school in September 2026. No school fees are payable.
States current and proposed arrangements concisely.
1.13
“The other parent pays £500 per month voluntary child maintenance by standing order under an agreement dated 1 October 2025. No court order or statutory calculation is in place.”
Matches the £6,000 annual figure later disclosed as other income.
1.15
N/A: no other court proceedings between the parties.
Uses N/A where the question does not apply.
1.16
Alex and the two children occupy the jointly owned family home. Alex proposes to remain there until financial arrangements are resolved.
Explains occupants, ownership and the proposed short-term arrangement.
Part 2 example: financial details
Part 2 is the largest section. It covers capital and income across ten sub-parts, followed by the capital and income summaries. The totals below are designed to reconcile exactly.
2.1 Family home example
Alex and their spouse are registered joint owners in equal shares. A local agent valued the home at £420,000 on 22 May 2026. The mortgage statement dated 31 May 2026 shows £186,500 outstanding. Fictional sale-cost estimates total £8,400, based on written estate-agent and conveyancing estimates rather than a generic percentage.
Worked property calculation
Current market value£420,000
Less mortgage£186,500
Less early-repayment penalty£0
Less estimated sale costs£8,400
Total equity£225,100
Alex's 50% interest, Total A£112,550
A suitable answer in the ownership box would be: “The property is registered in the joint names of Alex Morgan and Jordan Morgan. I understand our legal and beneficial interests to be equal. I do not contend that the Land Registry ownership differs from the true position.”
If ownership or beneficial shares are disputed, do not copy that sentence. State your actual position and the basis for it, and consider legal advice.
2.2 Other property
Alex has no interest in any other land or buildings, including overseas property. The answer is N/A and Total B is £0.
2.3 Bank and savings accounts
Form E asks for every personal bank, building society and National Savings account held at any time in the previous 12 months, including joint, overdrawn and closed accounts. Alex's sample table is:
Account
Balance
Alex's interest
Disclosure point
Everyday current account
£3,240
£3,240
Sole account
Online savings account
£11,800
£11,800
Sole account
Household joint account
£1,620
£810
50% interest shown separately
Closed regular saver
£0
£0
Closed 30 November 2025 but still within 12 months
Total C1
£15,850
Supported by 12 months of statements for each account
Use account numbers in the form and documents, but do not publish them in a public example. The closing balance of a joint account is not automatically the value of your personal interest; explain the share used.
2.4 to 2.8 Other personal assets
Investments, C2: cash ISA £8,750 and employer shares £2,400, giving £11,150.
Life policies, C3: one term-assurance policy with no surrender value, giving £0. The policy is still identified because section 2.5 includes policies without a surrender value.
Money owed to Alex, C4: confirmed former energy-account refund of £210.
Cash above £500, C5:£800 held as household emergency cash, with location and currency stated.
Belongings individually worth more than £500, C6: car £9,500 and watch £1,200, giving £10,700.
Total C therefore equals £15,850 + £11,150 + £0 + £210 + £800 + £10,700 = £38,710.
2.9 and 2.10 Liabilities and Capital Gains Tax
Alex lists a sole credit card balance of £2,180, a personal loan of £6,700 and a store card with a nil balance. The mortgage is not repeated here because it is already included in the home calculation. The form also says not to repeat overdrawn bank accounts as liabilities.
Total D1 liabilities: £8,880.
Total D2 estimated Capital Gains Tax: £0 in this fictional example.
Total D: £8,880.
“No tax expected” should be an informed estimate, not a guess. Get tax advice where property, shares, businesses or other disposals may create a liability.
2.11 and 2.12 Business interests and directorships
Alex is not self-employed, has no partnership or company interest, and has not been a director in the last 12 months. Sections 2.11 and 2.12 are marked N/A, with Total E at £0.
2.13 Pensions
Alex has two defined-contribution arrangements. Each pension needs its own page or continuation entry, with the provider, reference, scheme type, valuation date, whether it is in payment and the cash equivalent figure.
Pension
Type
Valuation date
Cash equivalent
Current workplace scheme
Occupational defined contribution
20 May 2026
£84,600
Previous personal pension
Personal money purchase
15 May 2026
£21,300
Total F
£105,900
If a cash equivalent is not yet available, the official form asks for the estimated availability date and a copy of the request to the pension provider or administrator. Do not invent a pension value to make the form look complete.
2.14 Other assets
Alex has no trust interest, share options, assets held by another person, foreseeable inheritance or other asset not already disclosed. The answer is N/A and Total G is £0.
Use your own evidence
Ready to build your Form E from your own figures?
Start the guided questionnaire, save each section, and use the worked example to check the level of detail without copying fictional answers.
Section 2.20 pulls the capital totals together. Alex's completed summary is:
Reference
Description
Value
A
Interest in family home
£112,550
B
Other property
£0
C
Personal assets
£38,710
E
Business assets
£0
F
Pension assets
£105,900
G
Other assets
£0
Total assets
£257,160
D
Liabilities
£8,880
Assets less liabilities
£248,280
This is Alex's capital disclosure, not the combined marital asset pool and not a proposed settlement. Each party completes a separate Form E about their own financial circumstances.
Income example: sections 2.15 to 2.21
Alex's P60 shows gross employment income of £51,200 for the previous financial year, including a £2,000 non-guaranteed bonus. The current basic salary is £49,200. Based on the current payslips, Alex estimates net employment income of £37,440 for the next 12 months.
H, employment: £37,440 net for the next 12 months.
I, self-employment or partnership: £0.
J, investment income: £180 savings interest expected over the next 12 months.
K, state benefits: £0 received by Alex in this fictional example.
L, other income: £6,000 child maintenance, based on £500 per month.
The section 2.21 annual income total is therefore £43,620. Its monthly equivalent is £3,635, which is useful for comparing the annual income summary with the monthly budget in Part 3.
Consistency check
The £500 monthly maintenance appears in Part 1 as the current child-maintenance arrangement, in section 2.19 as £6,000 annual other income, and in the bank statements as regular receipts. The same fact is expressed consistently in three places.
Part 3 example: income and capital needs
Form E allows weekly, monthly or annual income-needs figures, but says not to mix periods. Alex uses monthly figures throughout. Household items that also benefit the children are included once in Alex's household needs; only separate child-specific expenses are placed in the children's column.
Monthly item
Amount
Basis
Housing
£1,350
Current mortgage and realistic future housing estimate
Council tax
£180
Current bill
Utilities
£260
Recent bills averaged
Food and housekeeping
£600
Recent spending reviewed
Transport
£320
Fuel, tax, servicing and public transport
Separate children's costs
£430
Clubs, school meals, uniform and trips
Insurance
£140
Current policy costs
Phone and internet
£90
Current contracts
Clothing and personal costs
£170
Annual spend divided by 12
Medical and dental
£70
Routine costs
Holidays, leisure and gifts
£260
Modest annual provision divided by 12
Home maintenance and other
£150
Evidence-led contingency
Total monthly income needs
£4,020
All figures use the same monthly period
Compared with average monthly income of £3,635, the example shows a £385 monthly shortfall. This does not determine the outcome; it simply makes the stated budget and available income arithmetically transparent.
Capital-needs example
Alex identifies a gross future housing need of £365,000 using three current listings for suitable three-bedroom homes near the children's schools, plus £8,000 estimated purchase and moving costs and £4,000 for essential initial work. Total capital need is £377,000.
A capital-needs figure is not automatically an amount the other person must provide. The evidence should show what is needed, while the wider case considers both parties' resources, borrowing ability and circumstances.
From example to complete form
Need field-by-field guidance for your own answers?
Use the full guide to understand every section, or start online when you are ready to turn your documents and figures into structured disclosure.
Last 12 months: “On 18 December 2025 I paid £6,000 from my sole savings account for urgent roof repairs to the family home. The payment appears in the December bank statement and the contractor's invoice is attached as an explanatory document.”
Next 12 months: “My £2,000 gross bonus in the last financial year was discretionary and is not guaranteed. It has therefore been excluded from my estimated employment income for the next 12 months. I am not aware of any other significant expected change.”
4.2 Standard of living
A concise sample answer is: “During the marriage we had a moderate standard of living funded mainly from employment income. We lived in a three-bedroom mortgaged home, used state schools, ran two ordinary cars and usually took one UK holiday each year. We did not employ domestic staff or maintain a second home.”
4.3 Contributions
Alex's neutral example says: “Both parties contributed through paid work, childcare and household responsibilities. I do not rely on any separate financial contribution beyond those ordinary family contributions.” If you rely on a specific contribution, identify who made it, when, the amount where relevant and why it should be considered.
4.4 Conduct
Alex writes “N/A: no conduct is relied upon.” The form itself says conduct is taken into account only in very exceptional circumstances. This box is not a general account of why the relationship ended.
4.5 and 4.6 Other circumstances and a new partner
Alex notes the children's need for stable housing near their schools and the September 2026 secondary-school transition. Alex has no known redundancy, inheritance or retirement event, no relevant agreement, and no new partner whose circumstances need to be disclosed.
Part 5 example: order sought
This is the least suitable section to copy from another person's Form E. It asks what orders you want the court to make, including the treatment of the family home, maintenance, clean break, pensions and property. Those choices can have lasting legal and financial consequences.
Illustration only
In this fictional case, Alex might state that the family home should be sold after suitable arrangements are made for the children, that the net proceeds should be divided, that pension sharing should be considered after complete pension disclosure, and that a clean break should take effect when any property, lump-sum and pension arrangements are implemented. This is not model wording or a recommendation for another case.
Where the appropriate order is uncertain, the form permits you to indicate the broad orders sought if you cannot yet be specific. Get legal advice before committing to a position where there are pensions, maintenance claims, disputed ownership, business assets, trusts, overseas assets or significant differences in earning capacity.
Example schedule of documents
The final schedule records whether each required document is attached, not applicable or to follow. Alex's core schedule would look like this:
Paragraph
Document
Example status
2.1
Home valuation obtained within the last six months
Attached
2.1
Recent mortgage statement
Attached
2.3
12 months of statements for every listed account
Attached, including the closed account
2.4
Latest ISA and share statements
Attached
2.11
Business accounts and valuation evidence
Not applicable
2.13
Recent cash equivalent for both pensions
Attached
2.15
Last P60 and three latest payslips
Attached
2.15
P11D
Not applicable: none issued
Alex also lists the roof-repair invoice as an additional explanatory document. Extra attachments should have a purpose and should be labelled so the reader can connect them to the relevant paragraph.
Weak and strong Form E sample answers
Question
Weak answer
Stronger answer
Property value
“About £420k.”
“£420,000 based on the attached agent valuation dated 22 May 2026.”
Bonus
“Sometimes.”
“£2,000 gross paid in February 2026; discretionary and not guaranteed, so excluded from the next-12-month estimate.”
Closed account
Omitted because the balance is nil.
Listed with closure date and 12 months of statements because it was held during the relevant period.
Future budget
“Housing £2,000.”
A realistic figure identified as current or future, using comparable rents, mortgage information or another stated basis.
Pension value
Estimated from an online account.
The requested cash equivalent and valuation date, or the provider request and expected date if still outstanding.
Final checks before signing Form E
Recalculate C1 to C6 and totals A to L. The figures copied to the summaries must match the detailed entries.
Check annual versus monthly figures. Income totals H to L cover the next 12 months; Part 3 can use weekly, monthly or annual needs but cannot mix periods.
Trace every figure to evidence. Note the statement, valuation, payslip or estimate behind it.
Search for missing accounts and pensions. Include dormant, joint, closed and small interests where the form asks for them.
Explain significant changes. Large transfers, asset disposals, bonuses, redundancy or expected changes should not appear without context.
Use N/A deliberately. Do not leave unexplained blank boxes.
Review the document schedule. Mark each item attached, not applicable or to follow accurately.
Read the statement of truth. Sign only after checking that the disclosure is full, frank, clear and accurate.
The current HMCTS Form E publication page provides the blank form and official notes, but does not list a completed sample Form E. Use examples to understand structure only and check every answer against the official form and your own evidence.
Can I copy answers from a completed Form E example?
No. You can follow the method, such as identifying the source of a valuation or showing an equity calculation, but the facts, figures and legal position must be your own.
What does a completed Form E look like?
It is the 30-page Form E with every applicable box answered, N/A used where appropriate, continuation sheets where needed, a completed document schedule, supporting evidence and a signed statement of truth. Get the watermarked sample PDF by email to see an example of the finished layout.
Is there an editable or Word version of Form E?
You can download the blank official Form E PDF free from GOV.UK. HMCTS recommends downloading it and opening it in Adobe Reader to fill it in; its download page does not list a Word version. Our completed sample contains fictional details and is a reference example. To prepare your own form, use the blank PDF or Divvio's editable questionnaire, which exports your answers to the official PDF.
Do I need to answer every box on Form E?
You should work through every question. The form says to write N/A where a box is not applicable. Do not leave a box blank merely because the answer is zero, unknown or still being obtained.
What balance should I use for a bank account?
Section 2.3 asks for the balance at the date of the financial statement and the current value of your interest. It also requires statements covering the previous 12 months for each relevant account.
What if my pension cash equivalent has not arrived?
Give the estimated date it will be available and attach a copy of the request sent to the pension provider, administrator or PPF Board, as applicable. Do not create an unsupported substitute value.
Should Form E income needs be monthly or annual?
You may use weekly, monthly or annual figures, but the form says to state which period you use and not to combine periods. This example uses monthly figures throughout Part 3.
Do both people complete the same Form E example?
No. Each person completes and exchanges a separate Form E about their own financial and other relevant circumstances. The two forms can then be compared and questions raised where information is missing or inconsistent.
Can a sample Form E tell me what order to ask for?
No. Part 5 is case-specific. The treatment of the home, maintenance, clean break, pension sharing and other orders depends on the facts and can require legal advice.
Get the printable Form E document checklist (PDF by email)
Every document in the official Form E Schedule of Documents — bank statements, pension CETVs, property valuations and income evidence — in a printable A4 PDF you can tick off as items arrive.
One email with the checklist. No spam.
Use the example to check your method, then disclose your own facts
Start the guided Form E flow, gather the evidence behind each figure, and use the complete guide when a section needs more explanation.